A Homeowner Guide to Contractor Insurance
A homeowner guide to contractor insurance matters most before the first board comes off your house. A new deck, replacement siding, roof repair, or interior remodel can improve your property for years. But if an accident, damage claim, or worker injury occurs during the job, the contractor’s insurance can determine whether the problem is handled professionally or becomes your financial burden.
For Greater Boston homeowners, checking insurance should be part of the same early conversation as scope, schedule, permits, materials, and price. A contractor should be comfortable explaining what coverage they carry and providing current documentation when requested.
What Contractor Insurance Protects You From
Contractor insurance is not one single policy. It is a group of coverages that can address different risks on a residential construction site. The right coverage depends on the project, but homeowners should understand the basic protections before signing an agreement.
General liability insurance is the starting point. It can respond if the contractor causes accidental property damage or bodily injury to someone other than their own employees. For example, a ladder could damage a neighbor’s vehicle, demolition work could break a window, or a delivery could create an injury hazard. Liability coverage is designed to address those types of third-party claims, subject to the policy’s terms and limits.
Workers’ compensation insurance addresses injuries to employees while they are working. This is especially relevant for roofing, siding, deck construction, framing, and structural repairs, where crews may work at height, use power tools, or handle heavy materials. If a contractor has employees, workers’ compensation is a major protection for both the worker and the homeowner.
Commercial auto coverage may also matter when company vehicles deliver materials, haul debris, or transport equipment to your property. Depending on the job, contractors may carry additional coverage for tools, equipment, or specialized risks.
Insurance does not make construction risk-free, and it does not replace good planning or careful workmanship. What it does provide is a financial backstop when an unexpected event occurs.
Homeowner Guide to Contractor Insurance: What to Request
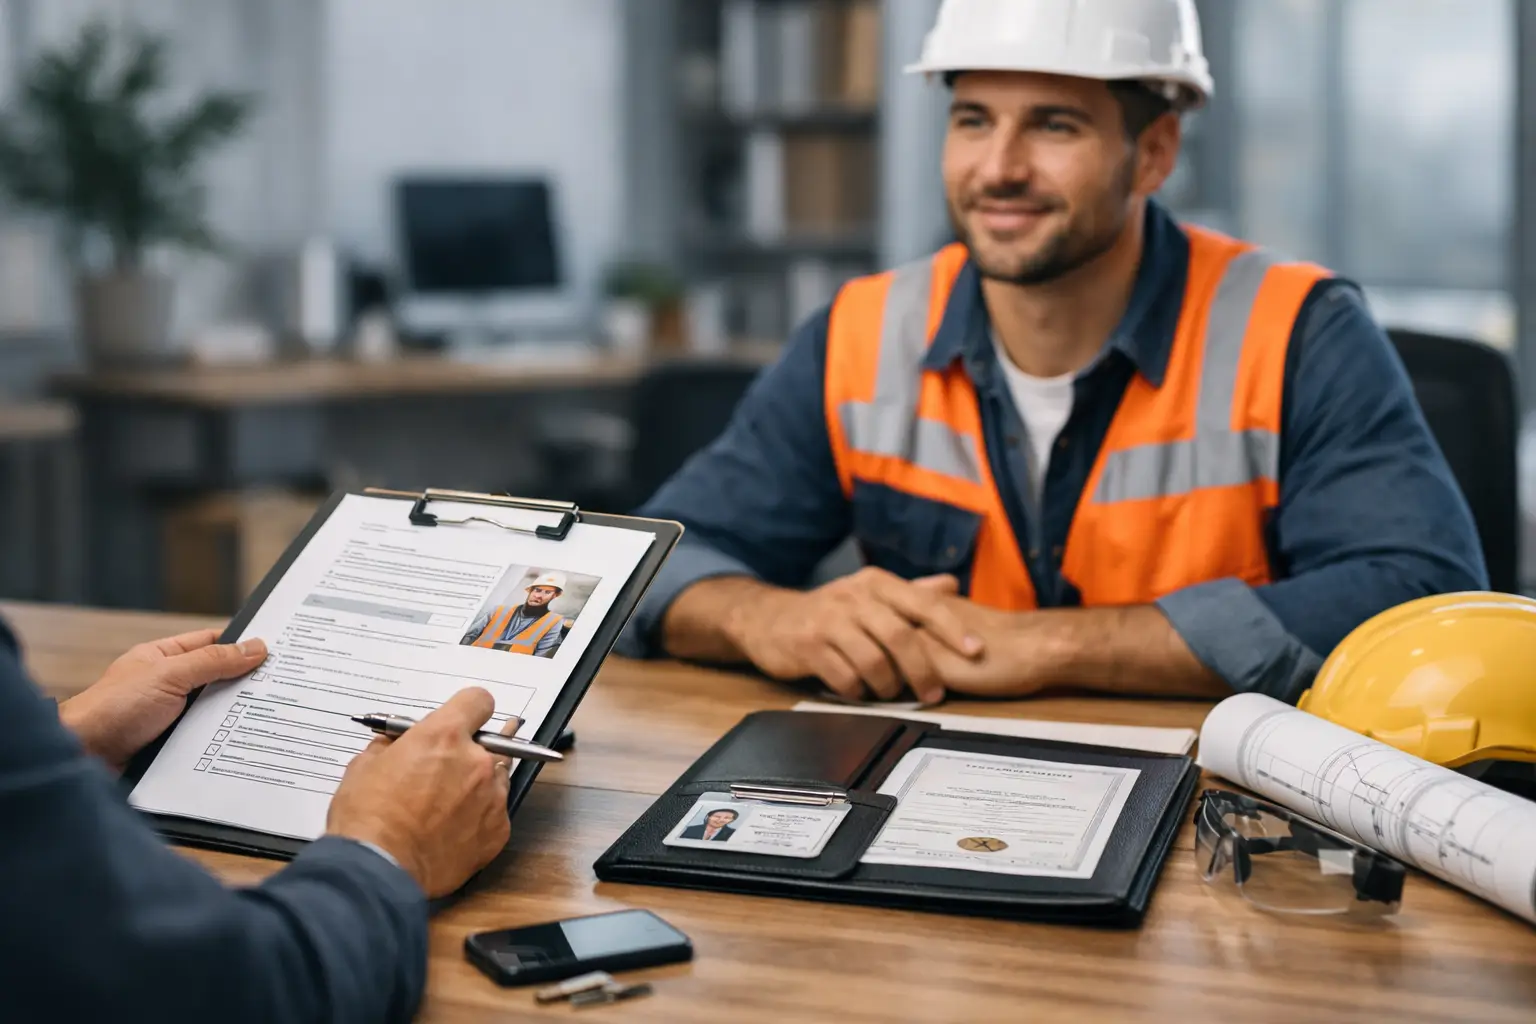
Do not rely only on a statement that a contractor is “fully insured.” Ask for a current certificate of insurance, commonly called a COI, before work begins. A reputable contractor should view this as a normal part of the hiring process, not as an unreasonable demand.
Review the certificate for the contractor’s legal business name, the policy expiration date, the insurance carrier, and the types of coverage listed. Make sure the name matches the business that will appear on your proposal and contract. A certificate for a different company, an expired policy, or vague paperwork deserves a follow-up question.
For a typical home improvement project, ask whether the contractor carries general liability and workers’ compensation coverage. If the contractor says they use subcontractors, ask how those subcontractors are insured and who is responsible for verifying their coverage. The general contractor should have a clear answer.
A certificate confirms that coverage was reported as active when it was issued, but it is not the policy itself and does not explain every exclusion or limit. For most homeowners, you do not need to become an insurance expert. You do need to confirm that current coverage exists and that the contractor is willing to document it.
If a project is large, unusual, or includes substantial structural work, consider speaking with your own insurance agent as well. Your agent can tell you whether your homeowners policy requires notice of the project or whether changes in vacancy, value, or construction conditions affect your coverage.
Why Workers’ Compensation Deserves Extra Attention
Homeowners often focus on accidental damage to the house. That is understandable, but worker injuries can create a more complicated situation when a contractor is uninsured or improperly classified.
A legitimate contractor with employees should be able to explain their workers’ compensation coverage. Be cautious when a contractor claims that every person on the crew is an independent contractor but cannot provide documentation, names of subcontracting businesses, or a clear description of who supervises the work.
This does not mean every small crew is a red flag. Many skilled tradespeople operate small businesses, and subcontractors are common on remodeling projects. The key is accountability. You should know who is performing work at your home, who manages the jobsite, and who carries the insurance responsibility.
For work involving elevated surfaces, structural framing, roof access, or demolition, this conversation is especially worthwhile. A lower bid is not a bargain if it depends on cutting corners with labor, safety, or insurance.
Insurance, Licensing, and Registration Are Different Checks
In Massachusetts, contractor credentials are not all interchangeable. Insurance, construction licensing, Home Improvement Contractor registration, permits, and code compliance each address a different part of a project.
Insurance helps address covered accidents and claims. A Massachusetts construction supervisor license, where required, relates to regulated construction work and building-code responsibilities. Home Improvement Contractor registration provides separate consumer protections for qualifying residential improvement work. Permits authorize specific work through the local building department.
A contractor can have one credential without another, so homeowners should verify the items that apply to their project. A deck replacement may require permits and code review for footing depth, framing, guards, stairs, and handrails. Roofing, siding, and finish work have their own project-specific requirements. The right builder will help explain what applies rather than making broad promises that no permit is needed.
Ask early who will pull permits, how inspections will be scheduled, and whether the scope includes corrections if an inspector identifies code-related work that must be addressed. Clear answers protect the schedule and prevent avoidable surprises.
Watch for Gaps Between the Proposal and the Jobsite
Insurance verification works best when it is connected to a clear written scope. Your proposal should identify the contractor, describe the work, outline payment terms, and explain who is responsible for materials, cleanup, permits, and coordination.
This is particularly helpful with labor-only arrangements. A labor-only contract may be a practical way to control material selections or budgets, but it should state who purchases materials, who handles damaged or delayed deliveries, and who is responsible for warranty coordination. Insurance may cover certain accidental losses, but it will not automatically resolve every product defect, owner-supplied material issue, or disagreement about scope.
The same principle applies to change orders. If hidden rot is found behind siding or a deck’s framing is more deteriorated than expected, the contractor should document the condition, explain the repair options, and price the additional work before proceeding whenever possible. Good documentation reduces confusion long before insurance is ever relevant.
Questions Worth Asking Before You Hire
A short conversation can reveal a great deal about how a contractor runs projects. Ask whether they carry general liability and workers’ compensation insurance, whether they can provide a current certificate, and whether subcontractors working on your project are insured.
Then ask practical job questions: Who is your day-to-day contact? Who will be on site? How will the work area be protected? What is the expected schedule? Who handles permits and inspections? How are change orders approved? A dependable contractor answers these questions directly because they are part of responsible project management.
Be wary of unusually low bids that provide little detail, requests for large cash payments, reluctance to use a written agreement, or pressure to start immediately without confirming the scope. Price matters, but so do communication, documentation, safety practices, and the contractor’s willingness to stand behind the work.
A Better Way to Start Your Project
Before construction begins, collect the proposal, verify appropriate credentials and insurance, confirm the permit plan, and make sure you understand the schedule and payment structure. Keep copies of all documents, including certificates, contracts, change orders, invoices, and final inspection records.
At LA Classic Builder, that preparation is part of a homeowner-focused process: a clear estimate, practical scope and planning, code-compliant construction, and a final walkthrough that confirms the finished details. The goal is not paperwork for its own sake. It is a project where responsibilities are clear and your home is treated with the care it deserves.
The best time to ask about insurance is when you are still choosing a contractor. A straightforward answer now can give you far more confidence once the work is underway.
Keep reading